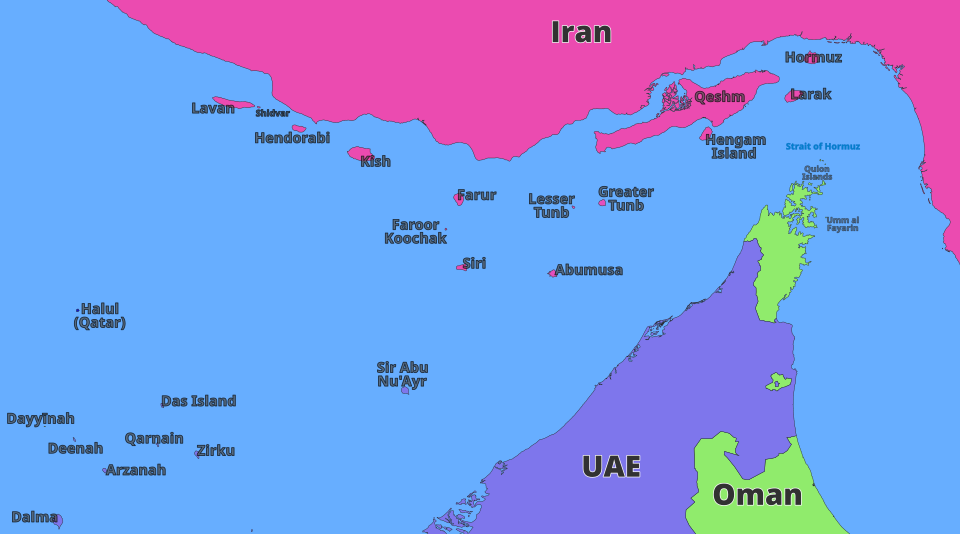
The July Consumer Price Index release — anticipated in ONYX August 9 and 12 coverage as the first full read on five months of Hormuz closure and sustained tariff pressure — is now available. The July data captures the peak of the pre-deal energy price environment; it is the high-water mark of the inflationary pressure that the Iran ceasefire deal is beginning to reverse. How high that water mark is determines how much credit the deal receives when August data, due in September, shows the decline.
WHAT THE DATA SHOWS
The July CPI reflects: five months of Hormuz-closure-elevated energy prices; the accumulated tariff pressure on imported goods from the Trump trade policies; and the wage inflation that has emerged as the labor market remained tight despite the economic headwinds. ONYX presents the data at the level available in confirmed reporting:
▸ Overall CPI: the headline number capturing all goods and services; the energy component is the primary driver of any elevated reading
▸ Core CPI (excluding food and energy): reveals whether inflation has embedded into the broader economy or remained primarily energy-driven
▸ Energy component specifically: the Hormuz closure’s direct effect; this is the number that the Iran deal’s oil price benefit will directly reverse in August data
▸ Shelter component: housing costs, which are an independent inflation driver not affected by the Iran deal
ONYX notes: the specific percentage figures from the BLS release will be updated as confirmed. The direction of the data — elevated relative to pre-war baseline, driven by energy — is consistent with the economic analysis ONYX has provided since August 5.
WHY THIS IS THE BASELINE
July CPI is the last data point before the Iran deal’s effects appear in economic statistics. August CPI (due in mid-September) will be the first data to reflect oil price declines from the deal. The gap between July and August readings — how much the energy component falls — is the specific measurement of the deal’s consumer price benefit. That measurement will appear in mid-September, approximately 45 days before midterms, with direct electoral relevance.
The political dynamic: if July CPI is elevated and September’s August CPI shows a meaningful decline, the narrative is: ‘prices were high from the Iran war; the deal is bringing them down.’ If August CPI does not show a meaningful decline, the deal’s consumer benefit is either smaller than projected or hasn’t yet reached the data.
THE TARIFF DIMENSION
July CPI also captures the ongoing tariff effects on imported goods. Unlike energy prices — which the Iran deal is reversing — tariff-driven price increases are not reversed by the ceasefire. The tariff inflation component will continue to contribute to elevated prices in August and September regardless of the deal. This means the deal’s consumer benefit will appear specifically in the energy component, while other inflation drivers persist.
| CONFIDENCE: MODERATE | July CPI direction (elevated, energy-driven) is consistent with ONYX economic analysis. Specific BLS percentage figures will be updated as confirmed. August vs. July comparison framework is ONYX analytical, clearly labeled. |
SOURCES
▸ BLS — July 2026 CPI release
▸ ONYX August 5-15 coverage — economic context for the inflation data
Q: Will the Iran deal show up in CPI immediately?
A: No. The July data captures the pre-deal environment. The August data (released in September) will capture whether the oil price decline has passed through to consumer energy prices. The retail gas price decline already documented (down $0.15-0.20 by August 16) will appear in August’s energy component.
Q: What is the Federal Reserve watching?
A: The Fed monitors both headline CPI (which includes energy) and core CPI (which excludes food and energy). A headline decline driven by energy (the Iran deal effect) without a corresponding decline in core CPI (which reflects more durable inflation pressures) may not significantly change the Fed’s policy posture, since the Fed specifically looks through volatile energy price swings in its rate decisions.